Cobertura SUM en Nueva York: lo que todo conductor debe saber
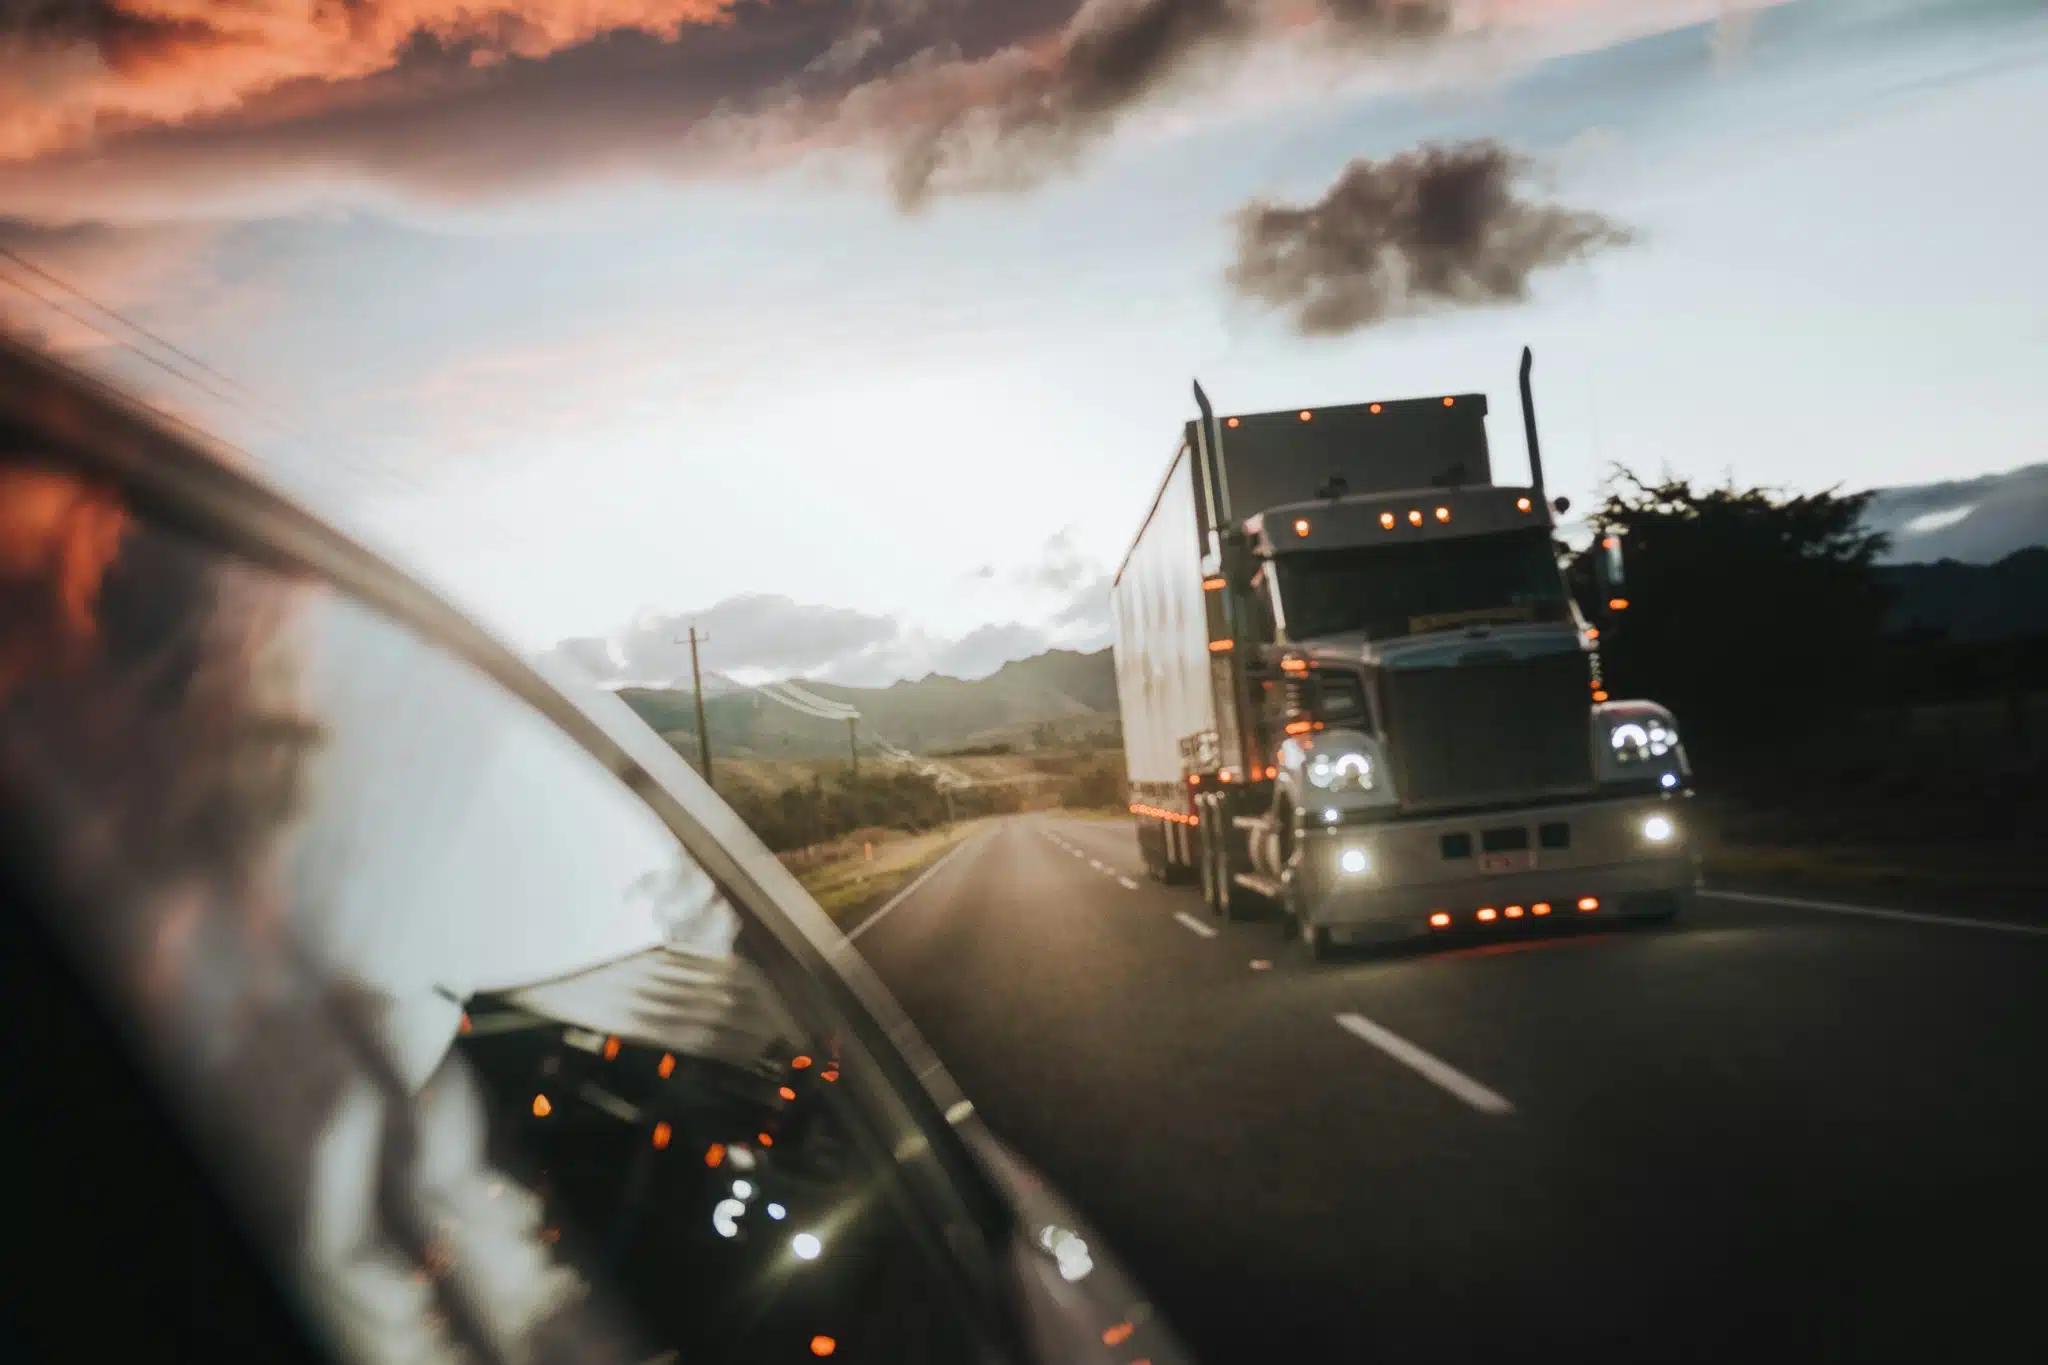
Imagine cruising along a busy interstate when an 18-wheeler suddenly swerves into your lane. The impact is violent. Your car slams into a guardrail. The truck driver fled the scene, and was never identified. As a result, you are left with zero recoverable insurance. Medical expenses start to mount, therapy sessions add up, and your life is forever altered.
Who pays for damages caused by uninsured drivers or hit and run drivers? Far too often, the cost of your medical coverage falls not on the at-fault driver, but solely on your own personal auto policy. This scenario is part of a growing nationwide crisis involving uninsured or untraceable trucking operations.
Federal law mandates that interstate tractor-trailers carry at least $750,000 in liability insurance. Yet gaps persist: specialized insurers serving trucking fleets lack state funding protections. When they fail or operators cut corners, victims are left exposed. Independent drivers and rogue carriers sometimes let policies lapse amid soaring premiums. The result? Injured motorists must turn to their personal uninsured or underinsured motorist (UM/UIM) coverage to recover anything at all.
Supplementary Uninsured/Underinsured Motorists coverage, commonly known as SUM coverage, is the layer of protection that fills this gap. It is one of the most valuable, and most misunderstood, components of a New York auto insurance policy. The personal injury attorneys at Martin & Colin, P.C. have spent decades helping injured New Yorkers recover the full value of their SUM claims, and this guide explains what every driver in the state should understand about this coverage.
A Case Study
A recent case illustrates exactly why drivers cannot rely on the other party’s insurance to make them whole after a serious collision:
In 2024, a young driver was struck by a semi-truck that crossed into her lane, sending her vehicle into a guardrail. She suffered a fractured leg that required two surgeries; the truck driver fled the scene and was never identified. The crash interrupted her daily activities, ended her participation in horseback riding, and tennis during recovery, and caused lasting post-traumatic stress. Her medical payments totaled more than $186,000.
With no identifiable driver or commercial insurer to hold accountable, her family turned to their own auto policies. Two personal policies with combined uninsured motorist limits of $1.25 million became the only available source of compensation. The insurers initially offered roughly $450,000. The claim was ultimately resolved for approximately $850,000 in 2025.
This case offers a cautionary tale to drivers in New York state: when an at-fault driver flees, is uninsured, or carries minimum limits that fall far short of your expenses, your own Supplementary Uninsured/Underinsured Motorist (SUM) coverage becomes a critical lifeline.
What Is SUM Coverage in New York?
SUM coverage is a form of supplemental automotive insurance authorized under New York Insurance Law Section 3420(f)(2). It allows an injured driver, passenger, or covered family member to recover damages from their own insurance policy when the at-fault driver either has no insurance, or carries policy limits too low to compensate the injured person’s losses.
In plain terms, SUM coverage steps into the shoes of the at-fault driver’s insurance when that coverage runs out or never existed in the first place. The injured party files a claim against their own policy, and the insurer pays up to the SUM limit selected when the policy was purchased.
You can purchase SUM limits up to the amount of your own bodily injury liability coverage (commonly $250,000/$500,000 or higher). SUM protects against both fully uninsured motorists and underinsured ones—situations where a trucking company’s $750,000 policy still falls short of your catastrophic damages from medical bills, lost wages, pain and suffering, and more.
“Do I need supplemental uninsured motorist (SUM) coverage in New York?”
While there is no law mandating the purchase of SUM coverage, we strongly recommend raising your SUM to your liability limits (or at least $250,000 per person / $500,000 per accident). The added premium is typically modest: often just $50 to $150 annually. This simple change can literally save your financial future after a life-altering wreck.
New York’s minimum required uninsured motorist coverage is only $25,000 per person: an amount that rarely covers a single surgery, let alone long-term medical care, lost income, and pain and suffering. Increasing your SUM limits is one of the most affordable and important decisions a New York driver can make.
SUM Coverage vs. Mandatory UM Coverage: Understanding the Difference
New York drivers often confuse SUM with the uninsured motorist coverage that is already required by state law. The two are related but operate differently, and the distinction matters when a serious injury claim is filed.
Mandatory Uninsured Motorist (UM) Coverage
Every New York auto policy must include UM coverage at minimum limits of $25,000 per person and $50,000 per accident. This coverage applies only when the at-fault driver has no insurance at all, including hit-and-run situations where the responsible driver cannot be identified. Standalone uninsured motorist property damage (UMPD) is not available in New York.
Supplementary Uninsured/Underinsured Motorists (SUM) Coverage
SUM coverage is optional in most cases and extends protection in two important ways. First, it raises the available limits above the $25,000/$50,000 floor, often matching the policyholder’s own bodily injury liability limits. Second, it applies when the at-fault driver is underinsured, meaning they carry some insurance but not enough to cover the full extent of the injuries caused.
The SUM Claim Process: What to Expect
Filing a SUM claim is more complex than filing a standard third-party liability claim. The injured person is making a claim against their own insurance carrier, which means the relationship that felt cooperative during premium payments can quickly become adversarial when significant money is at stake.
Notice Requirements
New York SUM endorsements require the insured to notify the carrier of a potential SUM claim as soon as practicable. Failure to provide timely notice can be raised by the insurer as a defense to coverage. Notice should be in writing and should preserve the right to pursue the claim while liability and damages are being investigated.
Exhaustion of the At-Fault Driver’s Policy
Before SUM benefits become payable, the injured person generally must exhaust the at-fault driver’s available liability limits. This often requires a separate negotiation with the at-fault carrier, careful documentation of the settlement, and consent from the SUM carrier before any settlement is finalized. Settling the underlying claim without proper consent can extinguish the SUM claim entirely.
Arbitration
Most New York SUM disputes are resolved through arbitration rather than in court. The arbitration process has its own procedural rules, evidentiary standards, and strategic considerations. Choice of arbitrator, presentation of medical evidence, and economic loss documentation can have a substantial effect on the outcome.
Common Insurance Carrier Tactics in SUM Claims
Insurance carriers handling SUM claims still have a financial interest to minimize the amount paid, even when the claimant is their own long-term policyholder. Tactics frequently seen in New York SUM cases include disputing the severity of your injuries, arguing that pre-existing conditions are responsible for your symptoms, or that a delay in medical care reflects a lower claim value.
Beware the temptation of a quick settlement; many insurance companies will try to get you to settle before you’ve had time to explore your legal options (and, frequently, before the full cost of your injury is known). Early insurance settlements, while expeditious, rarely reflect the full value of your long-term losses.
Martin+Colin responds to all insurance claims with a healthy dose of scrutiny. We put facts first to determine the full scope of your injuries, and then work to apply those damages to your insurance policy structure. Call (914) 771-7711 to explore your legal options after a car accident.
How Martin & Colin, P.C. Helps Injured New Yorkers Recover Under SUM Coverage
Based in White Plains and serving clients throughout Westchester County and the greater New York region, Martin & Colin, P.C. has handled SUM claims arising from automobile collisions, pedestrian accidents, bicycle accidents, and commercial vehicle crashes for decades. We apply the unique procedural requirements of SUM litigation with strategic considerations involved in coordinating with the at-fault carrier, and the medical evidence necessary to maximize recovery.
Every case begins with a careful review of the available coverage, the injuries sustained, and the long-term impact on the client’s life and livelihood. Consultations are confidential and carry no cost or obligation.
If you or a loved one has been injured by an uninsured or underinsured driver anywhere in New York, the attorneys at Martin & Colin, P.C. are available to review your policy, evaluate your potential SUM claim, and explain your options. Call (914) 771-7711 to speak with a New York personal injury attorney about your SUM claim.
¿Está listo para contratar a los mejores abogados para llevar su caso?
¿Está listo para contratar a los mejores abogados para llevar su caso?

Bill Martin
Fundé Martin+Colin, P.C., un bufete en White Plains especializado en lesiones personales que ha logrado recuperar millones de dólares para personas lesionadas en todo el estado de Nueva York. A lo largo de mi trayectoria, he representado a clientes en algunos de los casos de accidentes más graves que ocurren en el estado: lesiones de trabajadores de la construcción y demolición, accidentes laborales y siniestros viales que involucran automóviles, camiones, motocicletas y peatones. Mi práctica también abarca casos de responsabilidad de los propietarios de inmuebles y negligencia por parte de arrendadores; esto incluye desde caídas y tropiezos hasta daños causados por escalones rotos o la falta de pasamanos. En cada caso, mi objetivo es el mismo: exigir responsabilidades a las partes negligentes y garantizar que mis clientes lesionados y sus familias reciban la compensación completa a la que tienen derecho. Mis clientes confían en mí porque combino un historial de resultados comprobados con un enfoque directo y sin rodeos. Explico el proceso en términos sencillos, lucho con determinación por cada cliente y trato cada caso con la atención que merece. Si usted ha sufrido lesiones en un accidente, comuníquese conmigo y con el equipo de Martin+Colin, P.C. para obtener una consulta gratuita.


